Check out more of our news
Home Loan Document Checklist: What to Prepare Before Applying
February 19, 2026 | Read Time 10 minutes

Applying for a home loan can feel overwhelming, especially if it is your first time. Between bank requirements, unfamiliar terms, and multiple forms to submit, many buyers get stuck before they even start. The good news is that most home loan delays happen for one simple reason: incomplete or disorganized documents.
This article serves as your pre-application checklist to help you prepare what banks usually ask for before you formally apply. Think of it as your quick reference page so you can gather documents ahead of time, avoid back-and-forth emails, and move through the loan process more smoothly.
If you want a deeper, step-by-step breakdown by applicant type, you can also check our Your Ultimate Home Loan Requirements Guide (For Locals & OFWs), which covers detailed requirements for locally employed, self-employed, and OFW borrowers, plus a downloadable checklist and FAQs.
Why preparing your documents early matters
Banks assess home loan applications based on three main things: who you are, how you earn, and what property you are buying. Missing even one document can delay evaluation, approval, or release of your loan.
Preparing early helps you:
- Spot missing or expired documents before submission
- Avoid rushed applications and last-minute stress
- Shorten approval timelines
- Improve your chances of getting approved on the first review.
Even if you are still comparing banks or deciding between Pag-IBIG and bank financing, having your documents ready puts you in a stronger position.
Personal Documents: Proof of Identity and Status
These documents help the bank confirm your identity, civil status, and basic eligibility as a borrower.
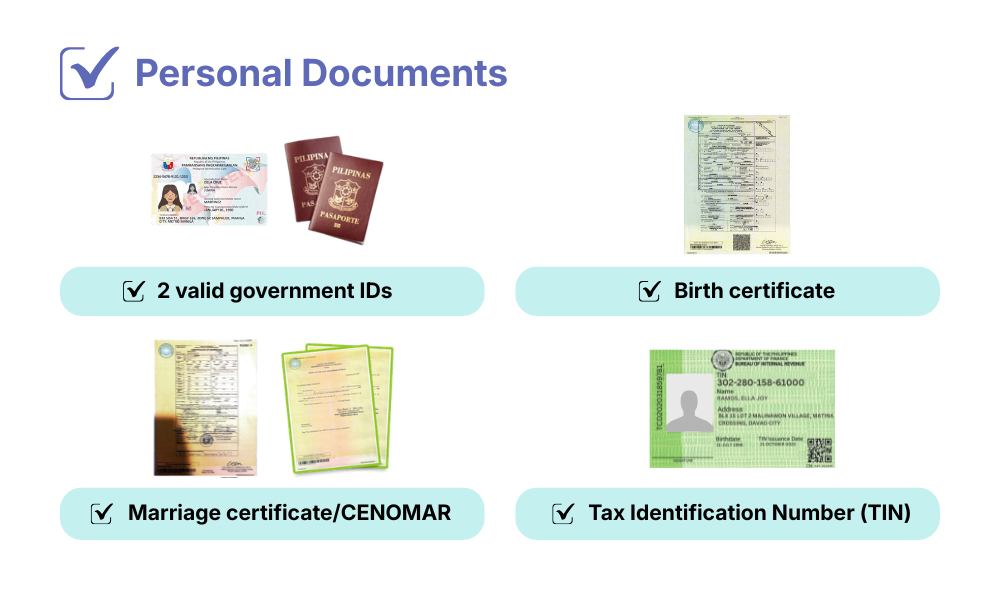
Common personal documents include:
✅ Valid government-issued IDs
Usually one or two IDs such as passport, UMID, driver’s license, or PRC ID. IDs must be clear, unexpired, and readable.
✅ Birth certificate
Used to verify personal details and identity.
✅ Marriage certificate If Married
Required to assess joint obligations and determine if a spouse must co-sign.
✅ Certificate of No Marriage (CENOMAR), If NOT married
Some banks may not require a CENOMAR but it is best to prepare it in case it is requested during the evaluation.
✅ Tax Identification Number (TIN)
Used for credit and income verification
✅ Special Power of Attorney (For OFWs)
Notarized locally and consularized abroad, granting authority to a representative for loan processing.
Income Documents: Proof that you can pay the loan
Income documents show your capacity to repay the loan. Requirements vary depending on whether you are locally employed, self-employed, or an OFW.
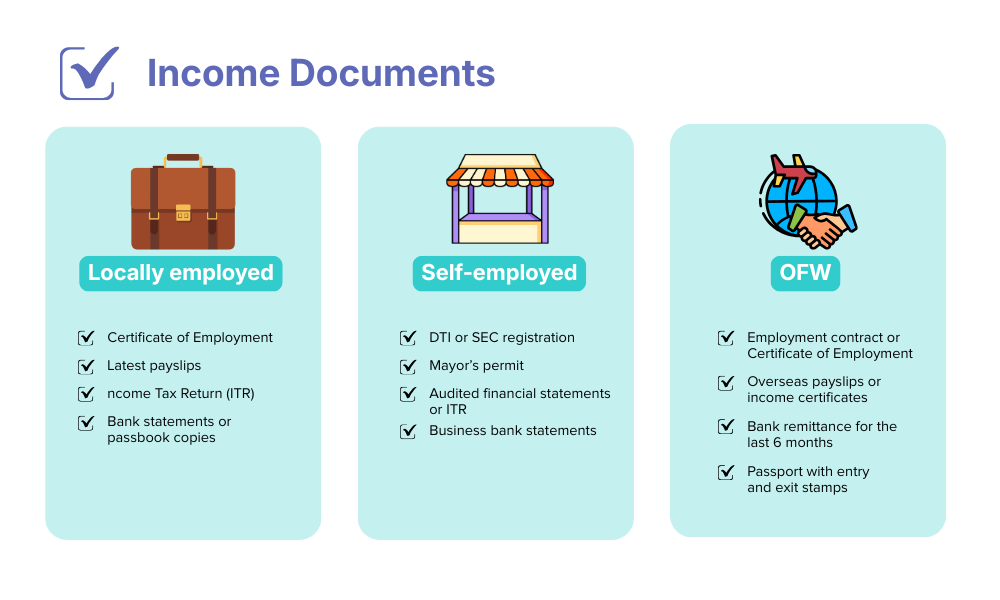
For locally employed applicants
✅ Certificate of Employment
Should include position, employment status, and length of service.
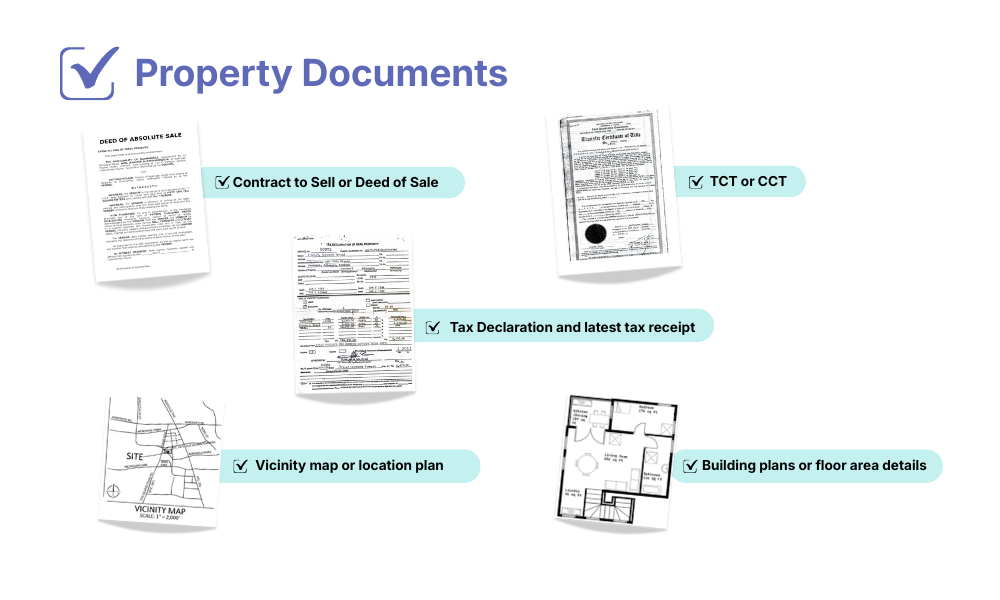
✅ Latest payslips Usually the last three months ✅ Income Tax Return (ITR) Often the most recent year, stamped or filed electronically ✅ Bank statements or passbook copies Typically the last three to six months ✅ Business registration documents DTI or SEC registration ✅ Mayor’s permit To confirm active business operations ✅ Audited financial statements or ITR Usually for the past one to two years. ✅ Business bank statements Helps banks assess cash flow consistency. ✅ Employment contract or Certificate of Employment Should be valid and clearly state position and salary ✅ Overseas payslips or income certificates Used to verify actual earnings ✅ Proof of remittances Bank remittance records for the last six months ✅ Passport with entry and exit stamps For a complete breakdown by applicant type, our Ultimate Home Loan Requirements Guide (For Locals & OFWs) walks you through each category in detail and explains why banks ask for these documents. Property Documents: Details about the home you are buying Property documents allow banks to assess the value, legality, and readiness of the property for financing. Commonly required property documents include ✅ Contract to Sell or Deed of Sale Shows agreed purchase price and payment terms ✅ Transfer Certificate of Title (TCT) or Condominium Certificate of Title (CCT) Used to verify ownership and property details ✅ Tax Declaration and latest tax receipt Confirms property classification and tax status ✅ Vicinity map or location plan Helps banks identify the property ✅ Building plans or floor area details Often required for house and lot purchases Banks might request more detailed documents during later stages, but having these ready speeds up the initial review. Must-Have vs Nice-to-Have Documents Document Type Must Have Nice to Have Valid IDs At least 2 — Proof of income (COE, payslips & ITR) ✓ — Bank statements ✓ Updated longer history Contract to Sell or Deed of Sale ✓ — Property title ✓ Certified true copy Marriage Certificate If applicable — Certificate of No Marriage (CENOMAR) — If applicable Proof of remittances (OFWs) ✓ Longer remittance history Financial statements (self-employed) ✓ Audited multi-year records Special Power of Attorney (SPA) ✓ (For OFWs) — Tips for Scanning, Naming, and Backing Up Documents Many home loan applications today are submitted digitally, so document quality matters. Follow these simple tips: Organized files help banks review your application faster and reduce chances of resubmission. What to do if you are missing documents Do not panic if you do not have everything yet. Some documents can be requested later, depending on the bank and loan stage. Start with the CORE REQUIREMENTS Once these are ready, you can already begin pre-assessment while completing the rest. Next Step: Check the full requirements guide This checklist is meant to help you prepare before applying, but every borrower’s situation is different. If you want a complete, detailed list of requirements, including: tips to organize documents and avoid delays, a downloadable printable checklist, answers to common document related questions, you can read Your Ultimate Home Loan Requirements Guide (For Locals & OFWs) and our step-by-step guide on How to Apply for a Housing Loan in the Philippines on our website. Get Guided Home Loan Assistance Being prepared is one of the easiest ways to make your home loan journey smoother, and this is where IDEAL Home Loan can help. Once you have your documents ready, you only need to submit them once. Our team reviews your application, helps check for missing requirements, and coordinates with multiple partner banks on your behalf.For self-employed applicants
For OFW applicants