Check out more of our news
Home Loan Approval: What Banks Look For
February 23, 2026 | Read Time 5 minutes

Banks don’t just approve loans based on income alone. They assess your overall financial profile, your documents, and even the property itself. Here’s a simple checklist most lenders use when reviewing a home loan application:
☑️Income stability and capacity to pay
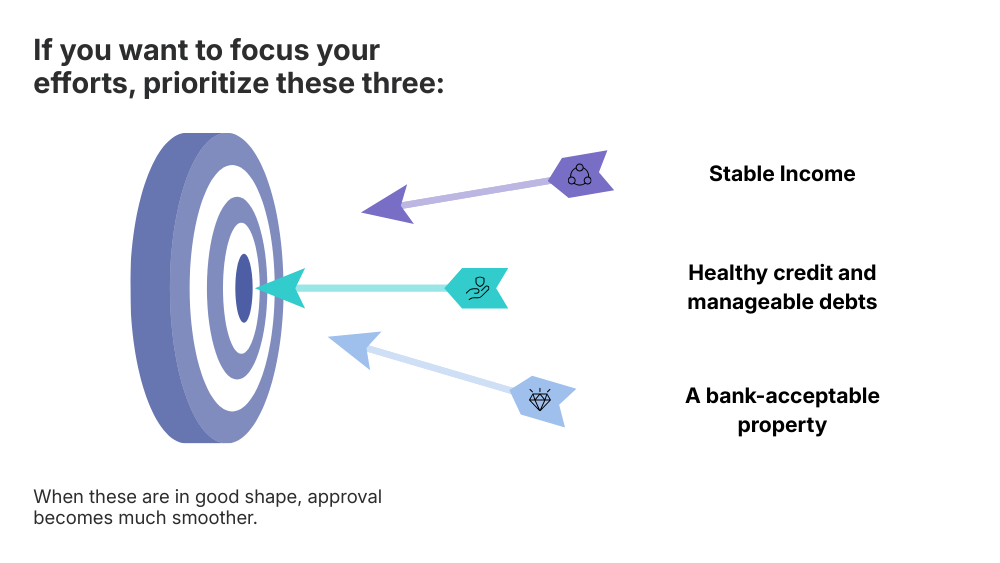
Banks prefer borrowers with stable, predictable income. Whether you’re locally employed, self-employed, or an OFW, lenders want to see that your income is consistent and sufficient to cover monthly amortizations over the long term.
☑️Complete and consistent documents
Even if you earn well, incomplete or inconsistent documents can slow things down. Banks carefully review submitted records to confirm identity, income, and financial capacity. Small discrepancies often lead to follow-ups and delays.
☑️Credit history and existing debts
Your credit history shows how you handle financial obligations. Banks check loan records, credit cards, and other debts to assess your payment behavior and debt-to-income ratio.
☑️Property quality and acceptability
The property you’re buying matters just as much as your finances. Banks evaluate location, title status, developer reputation, and overall property condition to ensure it’s acceptable collateral.
☑️Downpayment availability
A ready and verifiable downpayment signals financial preparedness. It also lowers the bank’s risk and improves your loan approval chances.
Red Flags That Can Delay Home Loan Approval
Some common red flags include frequent job changes, unclear income sources, high outstanding credit card balances, incomplete property documents, or sudden changes in loan terms. These don’t always mean rejection, but they often result in longer processing times and additional bank reviews.
Want a More Detailed Guide?
This checklist is just the starting point. For a deeper look at what banks actually require before you apply, read our Home Loan Document Checklist: What to Prepare Before Applying, which explains the most common personal, income, and property documents and how preparing them early can speed up approval.
It’s Easier With IDEAL Home Loan
Banks have different guidelines, and keeping track of them can take time. With IDEAL Home Loan, you submit your documents once, and our team helps review your profile, identify possible gaps, and guide you toward banks that fit your situation. We assist from pre-assessment through approval, helping streamline the process and reduce unnecessary delays as you move toward home ownership.