Check out more of our news
Can You Get a Home Loan with No Credit History?
February 23, 2026 | Read Time 7 minutes

Yes, you can, but it comes with more risk for banks. Without a credit history, lenders have no way to see if you reliably pay back borrowed money. This can make them cautious, sometimes requiring larger down payments or higher interest rates.
What do banks look at if you have no credit history?
Even without a formal credit record, banks consider other factors. They check your income stability, length of employment, savings, and proof of regular bills or rent payments. They want to be sure you can afford monthly loan payments.
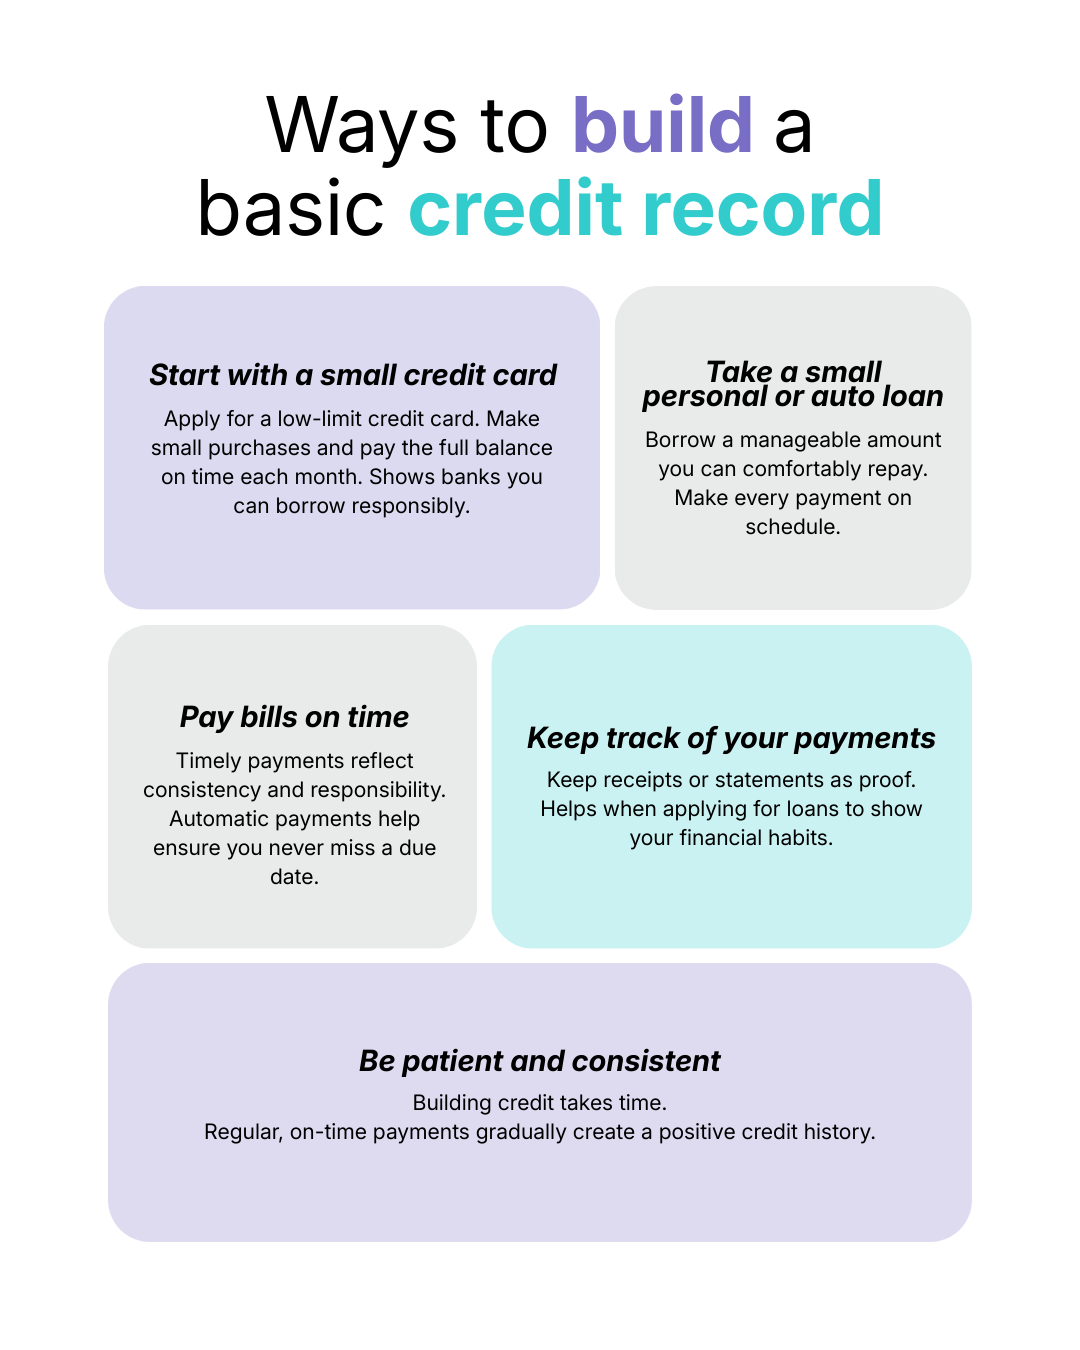
If you’re starting from scratch, simple steps can help. Getting a small credit card and paying it on time, using a personal or auto loan responsibly, or having your bills automatically paid on schedule can all create a positive record. Over time, this shows lenders that you are trustworthy.
Stable income and documents matter
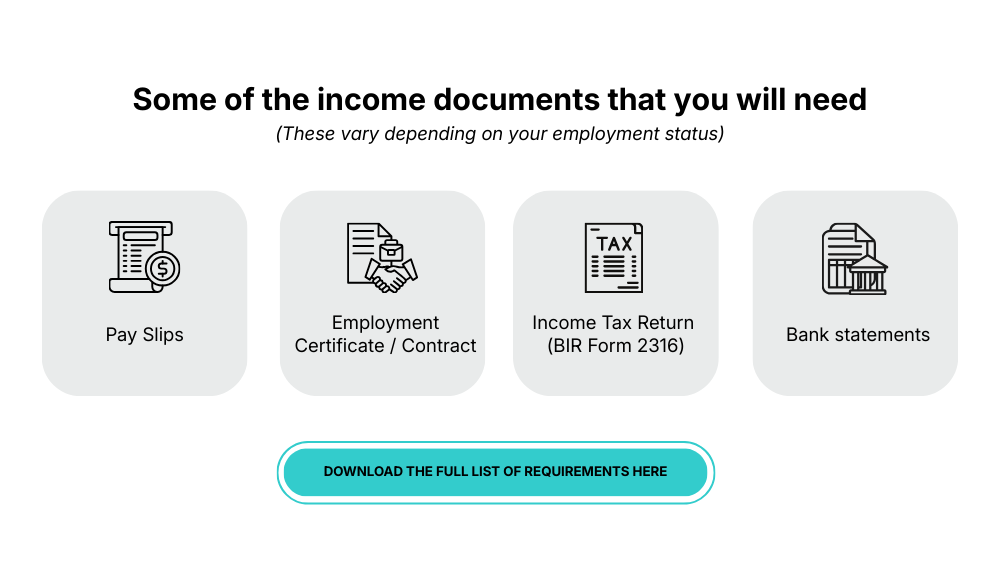
Banks rely heavily on proof of income. Pay slips, tax returns, or employment contracts are key. The more consistent your income looks, the easier it is to convince lenders to approve your loan.
Credit Cards vs Loan History
Think of credit cards and loan history as two different signals banks watch.
Credit cards show how well you handle monthly payments. Did you pay on time, or did you forget? They are great for building basic credit, especially if you’re just starting out.
Loan history, on the other hand, shows how you manage bigger, long-term commitments like car or personal loans. This matters more for home loans because it proves you can stick to regular payments over many years.
Credit cards help you get noticed, but loan history helps banks trust you with bigger amounts. Having both makes your home loan application much stringer
Your credit score is not the only thing lenders look at when you apply for a home loan. Banks also review your job stability, income, and savings to see if you can manage monthly payments. If you have little or no credit history, you may need to accept certain trade-offs, like a higher interest rate. The good news is that once you build your credit and payment record, you may qualify to refinance and get better terms later on. After choosing a lender, you can talk through the options that best fit your situation. Take the first step toward homeownership by applying for a home loan and exploring the loan options available to you.The bottom line: It is possible to get a home loan with no credit history